Can a Credit Report Error Cost You a Mortgage? What We Took Away From NAMB National 2026
Can a Credit Report Error Cost You a Mortgage? What We Took Away From NAMB National 2026
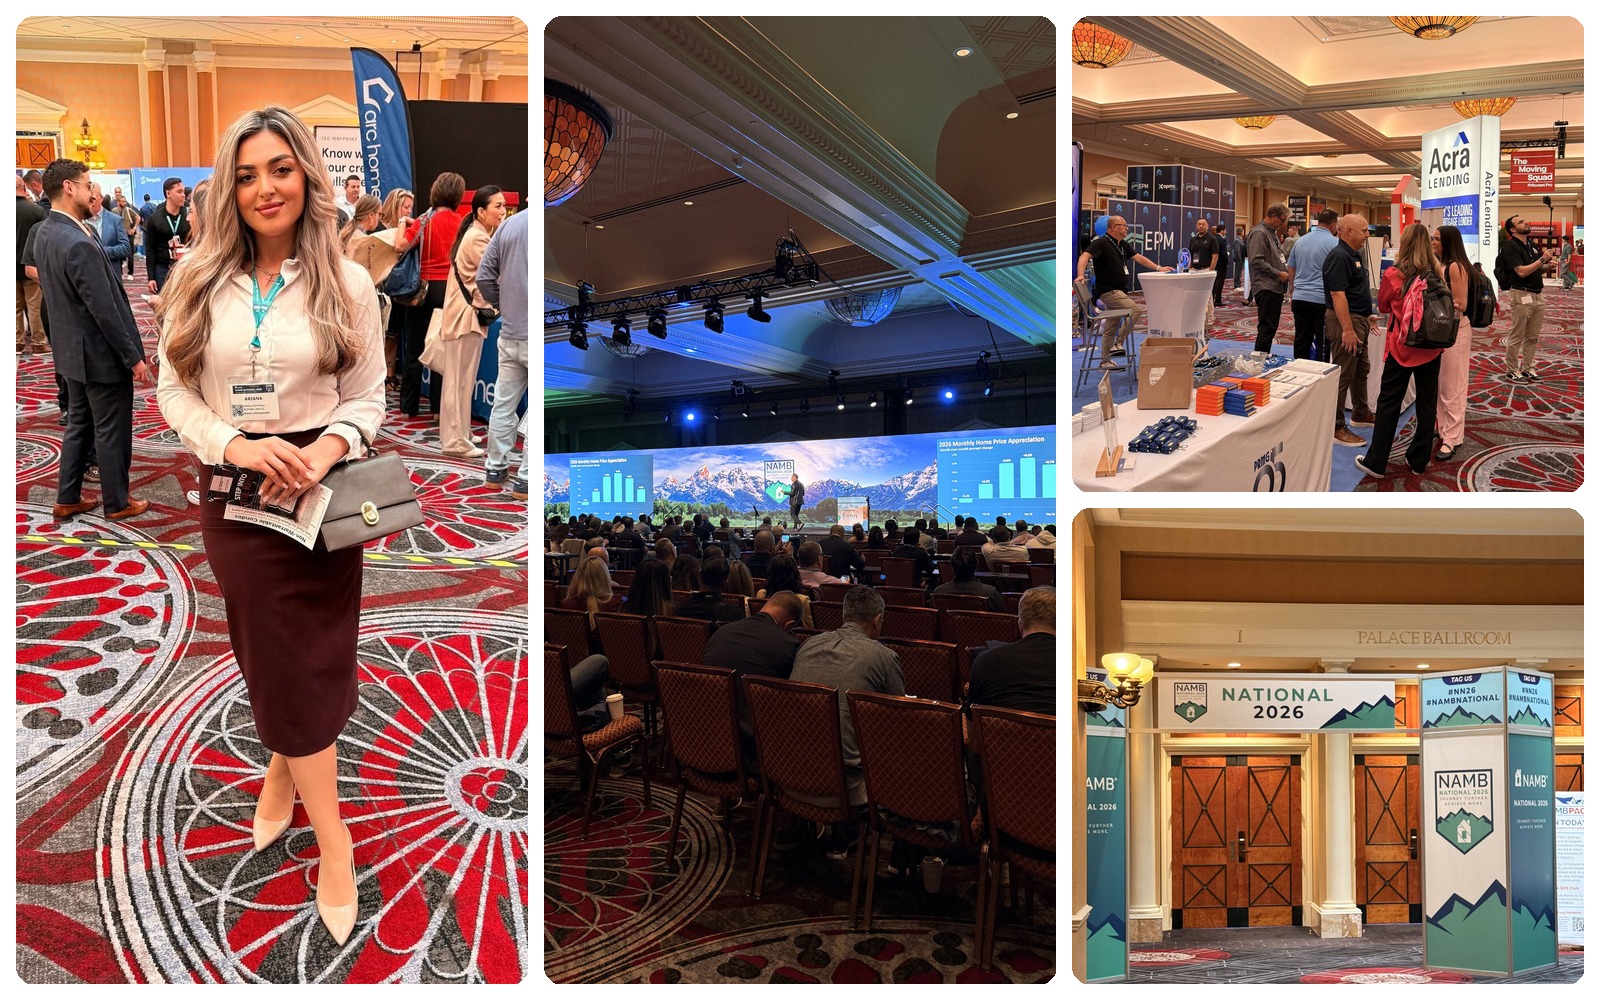
Yes, a single mistake on your credit report can be the difference between a mortgage approval and a denial. That’s a big part of why our team spent time with mortgage professionals at NAMB National 2026 in Las Vegas, hosted by the National Association of Mortgage Brokers.
Our colleague Ariana Munteanu spent the event meeting brokers and lenders, trading ideas, and talking about how we can work together. The conversations were the best part. Mortgage brokers sit right where credit report errors do the most damage, and they often see the problem before the borrower even knows it exists.
How common are credit report errors?
In its most recent full-scale study (published in 2013), the Federal Trade Commission found that about 1 in 5 consumers had an error on at least one of their credit reports, and roughly 5% had errors serious enough to lead to worse terms on loans and other credit. No comparable study has been done since, which is part of why we think this issue deserves more attention.
What does a credit report error look like during a mortgage application?
Errors show up in a lot of forms, for things like:
- Accounts that aren’t yours, often from identity theft or a mixed credit file
- Paid or settled debts still showing as unpaid
- The same collection account listed more than once
- Late payments you never made
- Being reported as deceased when you’re very much alive
To you, it usually sounds something like this: “We’re unable to approve your application based on information in your credit report.”
What should you do if a lender denies you because of your credit report?
You have rights under the Fair Credit Reporting Act (FCRA), the federal law that requires credit bureaus to keep your report accurate. Here’s where to start:
- Read your adverse action notice. This is the letter a lender must send when it turns you down based on your credit report. It should say a credit report was used and give the name, address, and phone number of the company that prepared it.
- Get a free copy of that report and look for anything that’s wrong.
- Dispute the error with the credit bureau. The bureau generally has about 30 days to investigate.
- Talk to us if the error isn’t fixed or if it already cost you a home, a rate, or a deadline.
Are you a mortgage professional?
We’d love to keep the conversation going. If you’re working with a borrower whose file doesn’t add up, there may be a fix, and we’re glad to be a resource for your clients.
A big thank you to NAMB for bringing everyone together, and to everyone we met in Las Vegas. We left with new connections, fresh ideas, and plenty to look forward to.
Think a credit report error cost you a mortgage?
We’ll review your credit report, examine the errors you’ve spotted, and talk about the evidence you’ll need. Your consultation is always free, and if we take your case, you won’t pay out-of-pocket or upfront fees because the Fair Credit Reporting Act makes the credit bureau pay.
Credit Report Resources
- How To Dispute Credit Report Errors
- Marked as Deceased on Your Credit Report? What To Do Next
- Fix Credit Report After Identity Theft
- Fix Tenant Screening Report Errors
- Denied a Mortgage Due to Your Credit Report?
- Denied a Loan Due To Your Credit Report?
- Why Your TransUnion, Equifax, and Experian Scores Are Different